
Poland’s supermarket sector has gone through rapid digital change over the past decade.
Four forces have reshaped the country’s retail technology ecosystem:
- Fiscal compliance reform.
- Large-format grocery expansion.
- Discount growth.
- Rising warehouse automation.
Polish-headquartered technology providers now play a structural role. They power POS systems, ERP platforms, logistics software and store infrastructure used across domestic supermarket networks.
Retail Technology Companies in Poland are led by a concentrated group of domestic IT and systems providers. They supply these products directly to supermarket chains:
- ERP.
- POS.
- Fiscal hardware.
- Warehouse software.
- Retail analytics.
In 2026, market leadership reflects scale, fiscal integration capability and operational exposure to grocery distribution. It does not reflect pure IT turnover.
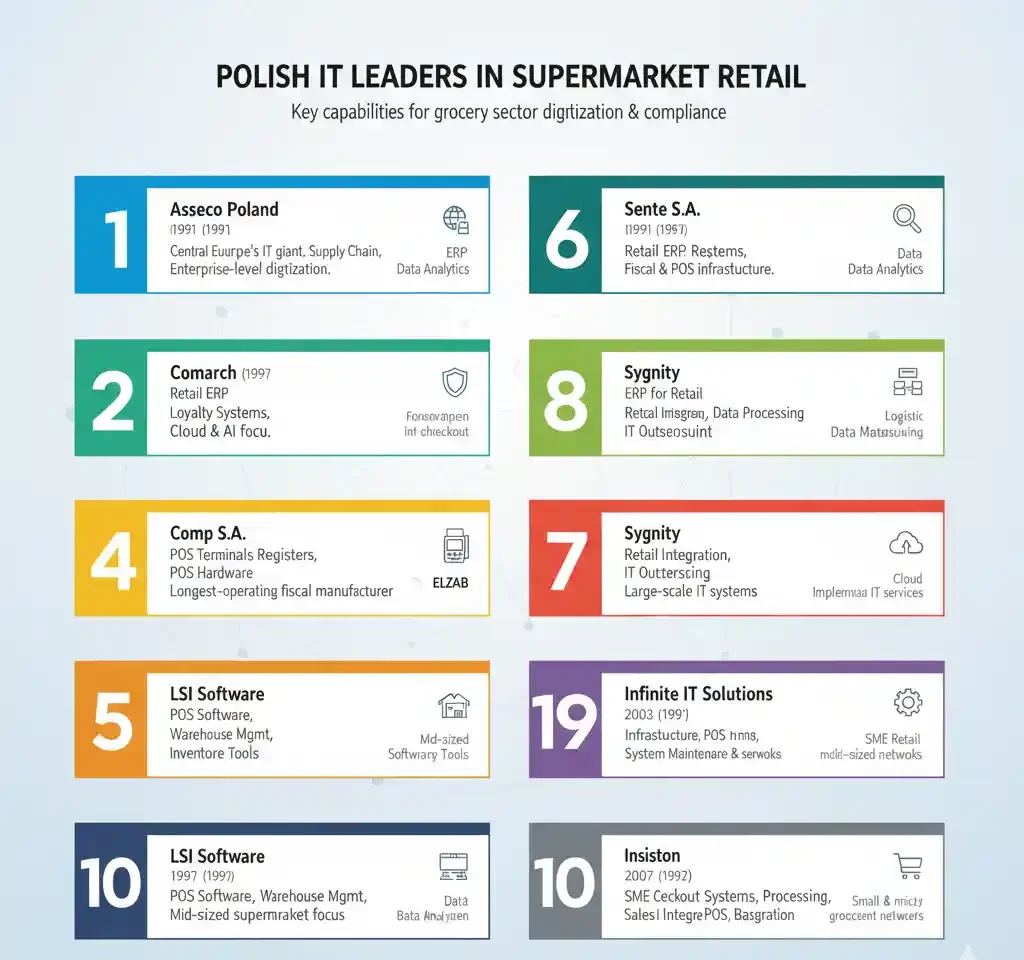
Top 10 Retail Technology Companies in Poland (2026)
| Rank | Company | Founded | FY2024 Revenue* | Core Retail Focus | Employees (approx.) |
|---|---|---|---|---|---|
| 1 | Asseco Poland | 1991 | €3bn+ (Group) | ERP, retail systems, integration | 30,000+ (Group) |
| 2 | Comarch | 1993 | €450m+ | Retail ERP, loyalty, omnichannel | 6,500+ |
| 3 | Comp S.A. | 1987 | €500m+ (Group est.) | POS, fiscal systems, retail infrastructure | 1,000+ |
| 4 | ELZAB | 1969 | €40m+ | Cash registers, fiscal devices | 300+ |
| 5 | LSI Software | 1991 | €20m+ | Retail management systems | 250+ |
| 6 | Sente S.A. | 2000 | Private | Retail ERP implementations | 200+ |
| 7 | Sygnity | 1991 | €200m+ | Public & retail IT systems | 1,500+ |
| 8 | Infinite IT Solutions | 2003 | Private | Retail integration & IT services | 300+ |
| 9 | Asiston | 2007 | Private | Retail POS software | 150+ |
| 10 | InsERT | 1992 | Private | SME retail software systems | 300+ |
*Revenue based on latest publicly available FY2024–FY2025 reports where disclosed. Some private companies do not publish full financials.
How This Ranking Was Built
This ranking evaluates Polish-headquartered companies that provide technology directly used by supermarket operators. The assessment is based on:
- Corporate revenue scale (FY2024–FY2025 where available)
- Verified supermarket and grocery exposure
- POS and fiscal system footprint
- ERP and warehouse system penetration
- Structural relevance to Poland’s grocery supply chain
- Operational scale and workforce
Companies focused purely on general enterprise IT without clear supermarket exposure were excluded.
1. Asseco Poland
Key facts
Asseco Poland was founded in 1991 in Rzeszów. It has grown into one of Central Europe’s largest IT groups.
Core supermarket-relevant capabilities include:
- Retail ERP systems
- Supply chain software
- Financial and fiscal integration systems
- Data analytics platforms
Why it matters to supermarket buyers
The group works across banking, public administration and telecom. Its retail technology integration arm supports supermarket chains with ERP deployments and fiscal compliance systems.
Its operational relevance is tied to enterprise-level supermarket digitisation.
Large grocery groups are consolidating IT platforms. Asseco’s scale and integration capacity place it at the top of Poland’s retail technology hierarchy.
Strategically, the company keeps expanding through acquisition-led growth across Central Europe.
2. Comarch
Key facts
Comarch was founded in Kraków in 1993. It has become a major European enterprise software provider.
Retail-focused solutions include:
- Comarch Retail ERP
- Loyalty management systems
- Omnichannel commerce platforms
- BI and analytics tools
Why it matters to supermarket buyers
The company has significant exposure to FMCG and supermarket chains, both in Poland and abroad.
In Poland’s grocery sector, Comarch’s loyalty and CRM systems are particularly influential. Discount and hypermarket competition is intensifying. Customer data infrastructure has become critical.
Comarch’s strategic direction emphasises cloud migration and AI-driven retail analytics.
3. Comp S.A.
Key facts
Comp S.A. was established in 1987. It plays a direct role in Poland’s fiscal and POS infrastructure.
Core offerings:
- POS terminals
- Fiscal cash registers
- Self-checkout systems
- Retail IT infrastructure
Why it matters to supermarket buyers
Comp’s subsidiary structure supports fiscal compliance. This is a key structural pillar in Poland’s supermarket system.
Its relevance is strongest in physical grocery retail environments. These include mid-sized supermarket chains and franchise formats.
Poland’s fiscal regulations keep evolving. Comp remains embedded in checkout infrastructure across the country.
4. ELZAB
Key facts
ELZAB was founded in 1969. It is one of Poland’s longest-operating fiscal device manufacturers.
Product focus:
- Fiscal cash registers
- POS hardware
- Retail software integration tools
Why it matters to supermarket buyers
ELZAB is smaller in revenue scale than Asseco or Comarch. Its devices remain widespread among supermarkets and food retailers.
The company’s structural importance is tied to fiscal digitisation requirements and mandatory reporting systems.
5. LSI Software
Key facts
LSI Software was founded in 1991. It provides retail management software systems with exposure to grocery and food retail.
Core capabilities:
- POS software
- Warehouse management modules
- ERP retail integration
- Inventory optimisation tools
Why it matters to supermarket buyers
The company’s footprint is strongest in domestic mid-sized supermarket operators.
Warehouse efficiency is becoming central to grocery margin stability. LSI’s WMS modules continue to support supply chain automation.
6. Sente S.A.
Key facts
Sente was founded in 2000. It specialises in ERP systems tailored to retail and distribution sectors.
Key supermarket-related functions include:
- ERP for retail chains
- Logistics integration
- Financial management systems
Why it matters to supermarket buyers
Sente is privately held. It has built a strong client base among Polish retail and distribution businesses.
Its operational relevance lies in backend process digitalisation. It is not in visible front-of-store technology.
7. Sygnity
Key facts
Sygnity was established in 1991. It delivers large-scale IT systems, mainly for public and enterprise clients.
Retail exposure includes:
- Retail integration projects
- Data processing systems
- IT outsourcing
Why it matters to supermarket buyers
Sygnity is not purely supermarket-focused. Its scale and infrastructure services still contribute to Poland’s broader retail IT landscape.
8. Infinite IT Solutions
Key facts
Infinite IT Solutions was founded in 2003. It provides systems integration and managed services.
Supermarket involvement includes:
- Retail infrastructure deployment
- POS integration
- IT system maintenance
Why it matters to supermarket buyers
Its relevance lies in implementation capability. It does not lie in proprietary product development.
9. Asiston
Key facts
Asiston delivers POS software solutions for retail chains.
It was founded in 2007. It focuses on:
- Checkout systems
- Retail transaction processing
- Integration with fiscal devices
Why it matters to supermarket buyers
The company mainly serves small and mid-sized supermarket networks.
10. InsERT
Key facts
InsERT was founded in 1992. It provides accounting and retail software solutions.
Core supermarket relevance includes:
- SME retail software
- Sales management systems
- Basic POS integration
Why it matters to supermarket buyers
InsERT is more prominent in SME segments. It remains relevant for independent grocery retailers.
Market Structure Impact
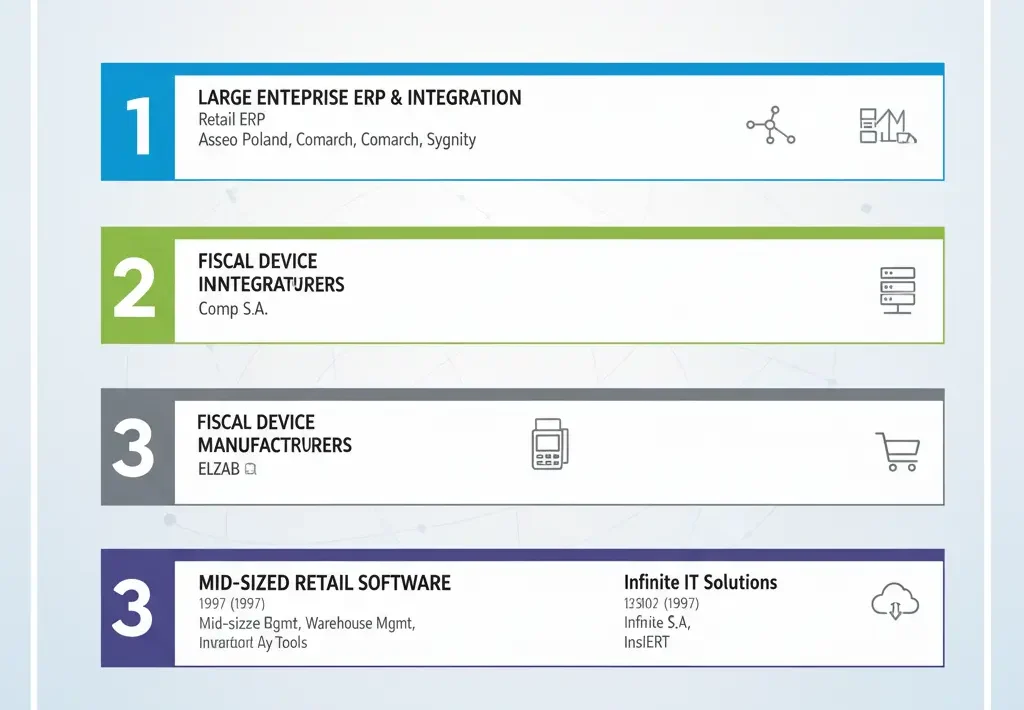
Poland’s retail technology structure is defined by three layers:
- Large enterprise ERP and integration providers
- Fiscal device manufacturers
- Mid-sized retail software specialists
In Western European markets, multinational vendors dominate. Poland keeps a strong domestic retail technology base.
This domestic concentration helps fiscal compliance adaptation and regulatory alignment.
Category Dominance Trends
Three categories dominate Poland’s supermarket technology spending:
- Fiscal POS infrastructure
- ERP modernisation
- Warehouse and logistics digitisation
Self-checkout and automation investment remains present. It is more moderate than in Western Europe.
Cloud migration continues gradually. Legacy infrastructure still plays a significant role in mid-sized chains.
Industry Direction 2026
Supermarket digitisation in Poland is expected to focus on:
- ERP consolidation
- Real-time reporting compliance
- Supply chain visibility
- AI-based inventory forecasting
However, investment cycles remain sensitive to retail margin pressure.
Domestic providers with fiscal and regulatory integration expertise keep a competitive advantage over global-only platforms in mid-tier grocery segments.
Frequently Asked Questions
Which retail technology company ranks first in Poland?
Asseco Poland ranks first. It was founded in 1991 and has group revenue of €3bn+. It supports supermarket chains with ERP deployments and fiscal compliance systems.
Why are Polish companies strong in supermarket technology?
Poland keeps a strong domestic retail technology base. This helps fiscal compliance adaptation and regulatory alignment.
Which technology categories dominate supermarket spending in Poland?
Three categories dominate: fiscal POS infrastructure, ERP modernisation, and warehouse and logistics digitisation.
Conclusion
Retail Technology Companies in Poland remain structurally embedded in the country’s supermarket ecosystem. Enterprise ERP leaders sit alongside fiscal device specialists and retail software firms. They power checkout, compliance and warehouse systems across the wider Poland supermarket sector.
Consolidation continues and regulatory requirements evolve. Integration between retail systems, logistics platforms and inventory reporting will become more critical.
This is especially true as sustainability reporting and traceability increasingly intersect with Poland packaging and supply chain compliance standards.
Operational depth and integration capability will decide long-term leadership in Poland’s grocery technology landscape.
Editor’s Note: This analysis is based on publicly available company financial reports, annual disclosures and corporate filings for FY2024–FY2025 where available. Revenue figures reflect latest published data. Private company revenue is included only where publicly disclosed.