
Finland’s FMCG sector is built on strong domestic manufacturing, cooperative ownership and food production for export.
Multinational brand groups dominate many European markets. In Finland, the grocery supply chain is still shaped strongly by national producers with deep retail integration.
Supermarket ranges are built around a few core categories:
- Dairy
- Meat
- Bakery
- Beverages
- Functional foods
Highly automated factories and closely coordinated logistics networks support supply.
This ranking identifies the largest FMCG brands in Finland by revenue. It uses the latest publicly available FY2024 financial disclosures. Where companies report group revenue that includes international operations, this is clearly indicated.
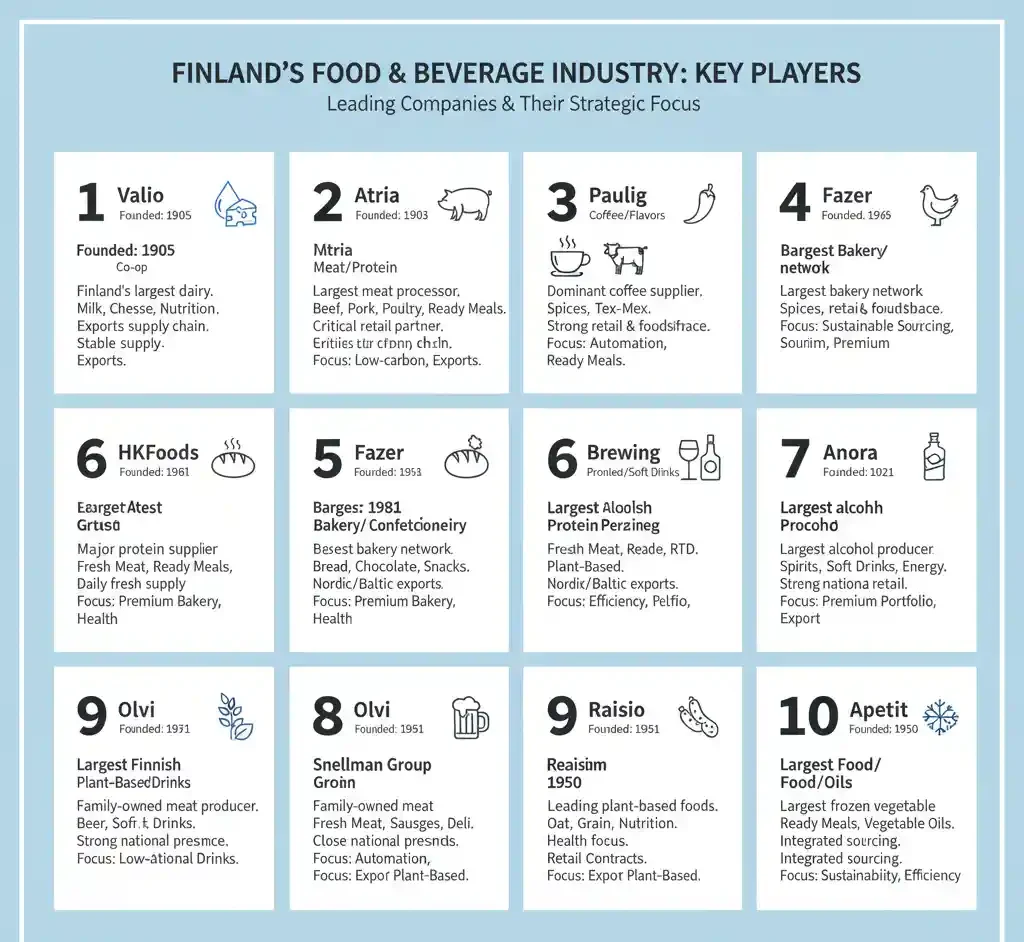
Top 10 FMCG Brands in Finland
| Rank | Company | Revenue (FY2024) | Scope | Category Strength | Employees |
|---|---|---|---|---|---|
| 1 | Valio | €2.28bn | Group | Dairy, nutrition | ~4,200 |
| 2 | Atria | €1.76bn | Group | Meat, ready meals | ~3,600 |
| 3 | Paulig | €1.20bn | Group | Coffee, spices | ~2,400 |
| 4 | Fazer | €1.18bn | Group | Bakery, confectionery | ~7,000 |
| 5 | HKFoods | ~€1.0bn | Group | Protein, ready meals | ~3,000 |
| 6 | Anora | €692m | Group | Alcohol beverages | ~1,200 |
| 7 | Olvi | €657m | Group | Beer, soft drinks | ~2,200 |
| 8 | Snellman Group | €462m | Group | Meat, deli | ~2,000 |
| 9 | Raisio | €227m | Group | Plant-based, grains | ~350 |
| 10 | Apetit | €163m | Group | Frozen foods | ~600 |
Scope note: Finland-only revenue is rarely published separately. Most leading brands operate export businesses across the Nordics and Europe. Figures above reflect consolidated group turnover.
1) Valio
Founded: 1905
Ownership model: Farmer cooperative
Valio is Finland’s largest FMCG producer. It is the central pillar of the national dairy supply chain.
The cooperative controls a major share of chilled dairy volumes sold through national supermarket groups. It also plays a key role in producing ingredients for export.
Its scale, processing footprint and farmer ownership give it long-term supply stability. Few competitors can match this.
Core product categories
- Fresh milk and cream
- Cheese and fermented dairy
- Infant and clinical nutrition
- Functional protein ingredients
Market position and scale
Valio supplies nearly all major grocery retail groups. It holds dominant shelf space in core dairy categories.
Its ingredient division exports to international food manufacturers and nutrition brands. Exports include:
- Lactose
- Whey proteins
- Specialty nutrition products
Operational relevance
- Multi-site dairy processing across Finland
- Integrated cold-chain logistics
- High automation in filling and packaging
- Key supplier to private label ingredient programs
Strategic direction
Continued investment in value-added nutrition, export growth and low-carbon dairy production.
2) Atria
Founded: 1903
Sector: Meat and protein processing
Atria is Finland’s largest meat processor. It is one of the country’s most important protein suppliers to grocery retail.
The company runs high-volume production facilities. It supplies both branded products and private label programs.
Its role in fresh meat and ready meals makes it a critical partner for supermarket chilled categories.
Core product categories
- Fresh beef, pork, poultry
- Processed meat
- Ready meals
- Convenience foods
Market position and scale
Atria products hold strong national shelf coverage. They also supply major foodservice and catering operators. The company maintains export sales across Nordic markets.
Operational relevance
- Large slaughtering and processing plants
- High private label contract volumes
- Integrated cold logistics
- Long-term livestock sourcing partnerships
Strategic direction
Focus on automation, ready-meal expansion and protein efficiency improvements.
3) Paulig
Founded: 1876
Sector: Coffee and flavor foods
Paulig is Finland’s dominant coffee supplier. It is also a leading player in flavour and ethnic food categories.
The company combines a strong branded retail presence with foodservice supply operations.
Its roasting and spice production capacity makes it one of the country’s key FMCG manufacturers.
Core product categories
- Roasted coffee
- Spices and seasonings
- Tex-Mex products
- Ethnic foods
Market position and scale
Paulig brands lead Finnish coffee shelves. They keep a strong presence in horeca distribution. The company exports across the Nordics and Central Europe.
Operational relevance
- Coffee roasting facilities
- Regional spice manufacturing
- Integrated packaging operations
- Direct retail logistics partnerships
Strategic direction
Expansion of sustainable sourcing programs and premium product ranges.
4) Fazer
Founded: 1891
Sector: Bakery and confectionery
Fazer runs Finland’s largest bakery manufacturing network. It is one of the country’s most recognisable food producers.
The company supplies fresh bread daily to national supermarket chains. It also keeps strong confectionery and snack brands.
Its scale gives it a central role in retail bakery supply.
Core product categories
- Bread and bakery products
- Chocolate and confectionery
- Snacks
- Foodservice bakery items
Market position and scale
Fazer products dominate bakery shelves. The company also supplies:
- In-store bakery concepts
- Restaurants
- Institutional catering operations
Operational relevance
- Large-scale baking facilities
- Fresh distribution logistics network
- Packaging innovation for bakery formats
- Multi-channel retail supply
Strategic direction
Growth in premium bakery categories, health-positioned products and export bakery expansion.
5) HKFoods
Founded: 1913
Sector: Protein and prepared foods
HKFoods is a major protein supplier. It serves both branded retail and contract manufacturing markets.
The company plays an important role in chilled food supply and convenience meal production. Its processing footprint supports large-volume supermarket supply programs.
Core product categories
- Fresh meat
- Ready meals
- Processed foods
- Plant-based protein
Market position and scale
HKFoods maintains strong retail distribution across Finland. It exports to Nordic and Baltic markets.
Operational relevance
- High-volume processing plants
- Packaging automation systems
- Integrated retail supply chains
- Contract manufacturing capability
Strategic direction
Operational efficiency improvements and expansion of plant protein categories.
6) Anora
Founded: 2021 (merger heritage)
Sector: Alcohol beverages
Anora is Finland’s largest alcohol beverage producer. It is a key supplier to both retail and horeca channels.
The group controls a broad portfolio of spirits, wines and ready-to-drink products. Its distribution network gives it a strong position in alcohol retail markets governed by strict rules.
Core product categories
- Spirits
- Wines
- Ready-to-drink beverages
Market position and scale
Anora supplies national alcohol retail systems. It exports across Northern Europe and global travel retail.
Operational relevance
- Bottling and beverage production
- Regulatory compliance operations
- Distribution and logistics network
Strategic direction
Developing more premium products and expanding export sales.
7) Olvi
Founded: 1878
Sector: Brewing and soft drinks
Olvi is Finland’s largest domestically owned beverage group. It is a major supplier to grocery and convenience retail.
The company combines beer production with growing soft drink and energy drink portfolios. Its bottling operations support high-volume retail distribution.
Core product categories
- Beer
- Soft drinks
- Energy drinks
- Mineral water
Market position and scale
Olvi maintains strong national shelf coverage. It supplies horeca customers across Finland.
Operational relevance
- Brewing facilities
- Bottling plants
- Beverage logistics infrastructure
Strategic direction
Growth in low-alcohol beverages and functional drink segments.
8) Snellman Group
Founded: 1951
Sector: Meat processing
Snellman is a family-owned meat producer with a strong reputation in Finnish grocery retail. The company supplies both branded and private label meat products.
Its production model is built around close cooperation with domestic livestock producers.
Core product categories
- Fresh meat
- Sausages
- Deli products
Market position and scale
Snellman holds strong shelf presence across national supermarket chains and regional markets.
Operational relevance
- Integrated meat processing
- Cold-chain logistics
- Private label manufacturing capacity
Strategic direction
Automation upgrades and expansion of retail contract production.
9) Raisio
Founded: 1939
Sector: Plant-based and grain foods
Raisio is Finland’s leading plant-based food producer. It has a strong focus on health and functional nutrition.
The company supplies both branded consumer products and ingredient-based solutions. Its portfolio aligns closely with changing consumer demand.
Core product categories
- Oat-based foods
- Grain products
- Functional nutrition
Market position and scale
Raisio maintains strong grocery distribution. It has export activity in selected European and Asian markets.
Operational relevance
- Specialised plant protein production
- Agricultural sourcing partnerships
Strategic direction
Expansion of export-oriented plant-based product lines.
10) Apetit
Founded: 1950
Sector: Frozen food and vegetable oils
Apetit is Finland’s leading frozen vegetable supplier. It is an important player in ready meal production. The company controls both sourcing and processing.
Its products hold strong positions in supermarket freezer categories.
Core product categories
- Frozen vegetables
- Ready meals
- Vegetable oils
Market position and scale
Apetit supplies national grocery chains and institutional foodservice customers.
Operational relevance
- Frozen food processing plants
- Agricultural raw material sourcing
- Cold storage logistics
Strategic direction
Sustainability-focused frozen food expansion and efficiency investments.
Category Dominance Trends
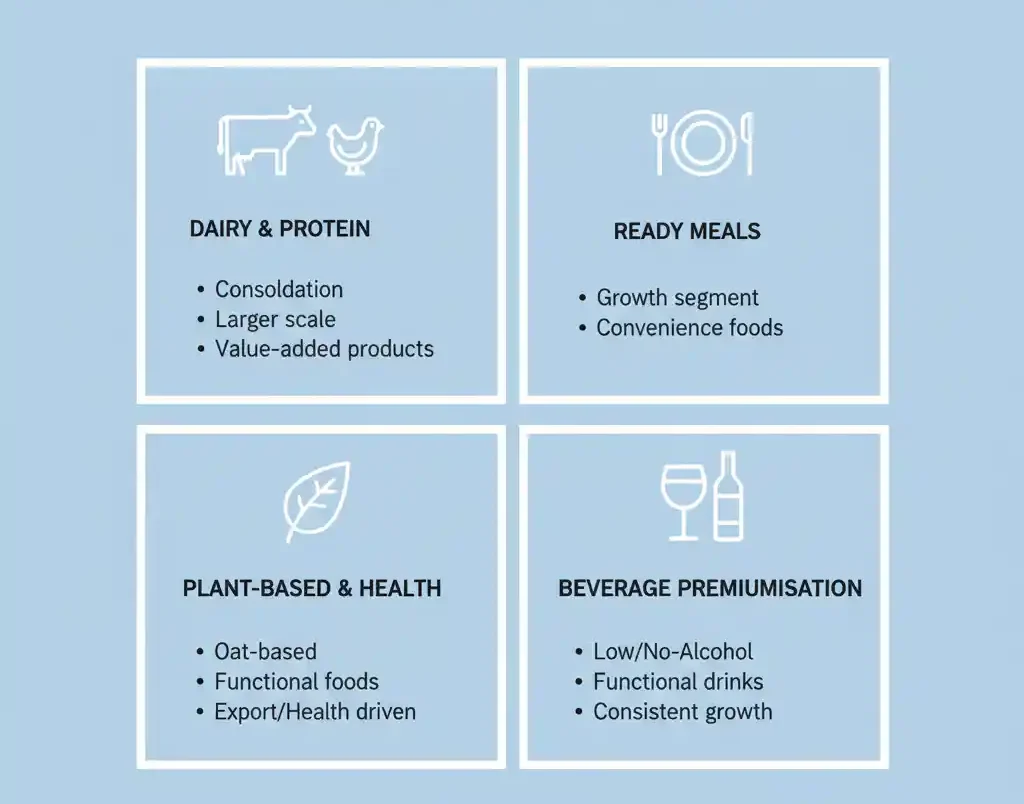
Several structural trends are visible:
Dairy and protein consolidation
Large-scale producers continue to absorb smaller processors. They are also expanding value-added product lines.
Ready meals growth
Convenience foods are now one of the fastest-growing revenue segments.
Plant-based expansion
Oat-based and functional foods are gaining shelf space. Export demand and health positioning drive this growth.
Beverage premiumisation
Alcohol-free, low-alcohol and functional beverage categories show consistent growth.
Industry Direction Outlook
Over the next two to three years:
- Automation investment will accelerate
- Packaging efficiency requirements will tighten
- Export volumes will increase
- Private label manufacturing partnerships will expand
- Sustainability compliance costs will rise
Finland’s FMCG producers are positioning themselves as regional manufacturing hubs rather than purely domestic suppliers.
Frequently Asked Questions
What is the largest FMCG brand in Finland by revenue?
Valio ranks first, with FY2024 group revenue of €2.28bn. It is a farmer cooperative founded in 1905.
Do the revenue figures cover Finland only?
No. Finland-only revenue is rarely published separately. The figures reflect consolidated group turnover.
Which trends are shaping Finland’s FMCG market?
The main trends are dairy and protein consolidation, ready meals growth, plant-based expansion and beverage premiumisation.
Conclusion
Finland’s largest FMCG brands continue to dominate supermarket supply chains. They do this through scale, production efficiency and export-driven growth.
Dairy, meat, bakery and beverages remain the core pillars of grocery turnover. Plant-based and convenience categories are gaining structural importance.
The structure of the Finland supermarket sector reinforces this dominance. A small number of large retail groups maintain close supplier relationships. This keeps categories stable over time and makes buying cycles predictable across national store networks.
At the same time, Finland private label programs continue to expand shelf presence across staple and chilled categories. Retailer-owned brands increasingly work with domestic manufacturers. This makes supply more secure while keeping margins under control.
The market remains characterised by strong domestic ownership, integrated manufacturing and close retailer collaboration. These factors will continue shaping Finland’s grocery market in the coming years.
Editor’s Note: This article is based on publicly available company financial reports, annual disclosures, and official statements for FY2024. Revenue figures reflect consolidated group reporting where Finland-only data is not separately published.