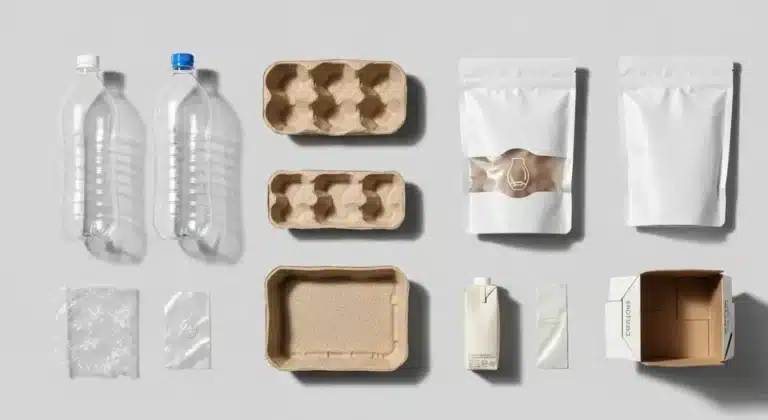

Europe’s leading mono-material food packaging suppliers include Amcor, Mondi, Coveris, Constantia Flexibles, Wipak, Südpack, ProAmpac, Huhtamaki, SP Group and Gruppo Happy.
For supermarket and FMCG buyers, the key question is not whether a pack can be described as mono-material. It is whether the complete structure can:
- protect the food
- run at commercial speed
- meet the recycling rules of the market where it is sold
That distinction matters. Food packaging is designed first to keep food safe and saleable.
Replacing a complex laminate with a simpler PE, PP or PET structure only creates value if performance stays acceptable. That covers barrier, sealing, puncture resistance, shelf life and packing-line efficiency.
EU Packaging and Packaging Waste Regulation requirements are speeding up that work. Suppliers are investing in:
- mono-PE, mono-PP and mono-PET structures
- thinner barrier layers
- recyclable lidding
- new sealing systems
The strongest converters are increasingly selling a complete transition service. This covers material science, print, machine trials, shelf-life validation and recyclability evidence.
Top mono-material food packaging suppliers in Europe
| Rank | Supplier | Core mono-material strength | Food applications | Why buyers shortlist it |
|---|---|---|---|---|
| 1 | Amcor | PE and PP recycle-ready flexible systems | Foodservice, dairy, snacks, proteins, pet food | Global scale and broad format capability |
| 2 | Mondi | Mono-PE, mono-PP and paper alternatives | Dry foods, pet food, pouches and bags | Integrated materials and converting |
| 3 | Coveris | MonoFlex PE and PP films | Bakery, produce, protein, convenience, pet food | European converting and machine validation |
| 4 | Constantia Flexibles | High-barrier recyclable flexibles | Food, confectionery, dairy and dry goods | Barrier and laminate engineering |
| 5 | Wipak | Food-grade recyclable flexible structures | Meat, cheese, convenience and medical | Strong food-protection expertise |
| 6 | Südpack | Mono-material thermoforming and lidding | Meat, dairy and ready meals | High-barrier protein applications |
| 7 | ProAmpac | Recycle-ready pouches and rollstock | Food, pet food and consumer goods | International programme capability |
| 8 | Huhtamaki | Flexible and rigid recyclable formats | Food, convenience and foodservice | Multi-format transition capability |
| 9 | SP Group | Mono-material food films and packs | Fresh and processed food | Food-focused European converting |
| 10 | Gruppo Happy | Mono-material rigid food packaging | Fresh food, meat and fish | Rigid tray and MAP capability |
1. Amcor
Amcor is one of the largest packaging groups operating in Europe.
Key facts
Following its combination with Berry Global, the group reports:
- around $23 billion in annual sales
- about 75,000 employees
- roughly 400 locations across more than 40 countries
What it supplies
For food buyers, scale is only part of the reason it ranks highly. Amcor’s AmPrima platform includes recycle-ready polyolefin structures.
Liquiflex AmPrima has been introduced in Europe for bulk foodservice products. These include sauces, soups, proteins and frozen vegetables.
The company is also developing recyclable formats across cheese, snacks and other grocery categories.
Why it matters to supermarket buyers
Amcor is most relevant where a retailer or FMCG group wants to move several categories toward common packaging principles. It avoids using a different converter for every format.
Buyers should still approve each structure by application and market. A group-level sustainability claim is not a substitute for the technical specification of the actual pack.
2. Mondi
Mondi combines flexible packaging conversion with its own paper and material capabilities.
What it supplies
Its food portfolio includes mono-PE and mono-PP structures as well as paper-based alternatives. This makes it useful when procurement teams are comparing more than one material route.
Mondi’s re/cycle FlexiBag uses MDO PE-based laminates. The group markets PE-based mono-material structures with barrier performance for dry foods and pet food. Its dried-food portfolio also includes mono-PP and mono-PE options with high-barrier configurations.
Why it matters to supermarket buyers
The buyer advantage is optionality. A project can begin with the functional requirement — shelf life, seal, print, line speed and recycling route. The material does not need to be chosen before the converter has assessed the product.
Paper alternatives are also attracting joint FMCG research, as GTN reports in its coverage of the PaperFlex Consortium.
The programme is separate from commercially available mono-material films. But it highlights the same need to validate food protection and manufacturing performance before changing a specification.
3. Coveris
Coveris has built its MonoFlex family around PE and PP laminates for food and non-food applications.
What it supplies
Formats include:
- horizontal and vertical form-fill-seal
- stand-up pouches
- pre-made bags
The food applications are broad. They cover bakery, confectionery, food-to-go, fruit and vegetables, pet food, protein and ready meals.
Why it matters to supermarket buyers
Coveris also offers shelf-life and machine validation. This is important because the move from a conventional laminate often fails at the packing line, not on a material datasheet.
For supermarket own-label teams, that end-to-end approach can reduce conversion risk. The converter can work through extrusion, print, sealing, shelf life and machine behaviour. This happens before a specification is rolled out across multiple manufacturers.
4. Constantia Flexibles
Constantia Flexibles specialises in technically demanding flexible packaging.
Its recyclable product development is especially relevant where a food needs oxygen, moisture, aroma or light protection. In the past, this protection came from a complex multilayer laminate.
What buyers should check
That is one of the hardest parts of the mono-material transition. Simplifying the structure without shortening shelf life requires careful barrier design.
Procurement teams should therefore compare oxygen transmission, water-vapour transmission and real product shelf-life trials. They should not select a structure just because it contains fewer material families.
5. Wipak
Wipak is deeply exposed to food applications including meat, cheese and convenience products. These are demanding categories. The pack is directly tied to food safety, leakage, shelf life and waste.
Why it matters to supermarket buyers
For buyers, Wipak is most relevant where a project needs technical support around thermoforming, lidding or high-barrier flexible structures.
Existing line references are valuable. A material already proven on comparable tray sealers or thermoformers usually carries less operational risk than a laboratory-only solution.
6. Südpack
Südpack has a strong position in high-barrier films for meat, dairy and convenience food. Its recyclable mono-material development includes thermoforming and lidding systems. This makes it especially relevant to protein and chilled categories.
What buyers should check
Protein packaging is a useful test of whether a sustainability claim survives commercial reality.
Punctures, weak seals or shorter shelf life can cause far more environmental and financial damage through food waste than simplifying the film saves.
Buyers should therefore measure pack failures and waste alongside packaging weight.
7. ProAmpac
ProAmpac supplies flexible packaging across food, pet food and wider consumer markets. Its portfolio includes recycle-ready pouches, bags and rollstock.
Its international footprint can suit multinational FMCG programmes, where a common design needs to be produced or supported in several countries.
European buyers should confirm:
- the manufacturing site
- the approved backup site
- the print technology
- the exact recycling assessment for the structure offered
8. Huhtamaki
Huhtamaki operates across flexible, fibre and rigid food packaging.
That breadth is useful when the commercial brief is not simply “move to mono-PE”. Instead, it may be “reduce packaging impact while maintaining food protection and line performance”.
For grocery buyers, the comparison should remain functional. Different materials need to be tested against the same product, shelf-life and logistics requirements before a decision is made.
Food-label specifications are facing the same scrutiny. GTN recently reported on UPM’s new grease-resistant food label paper. It was developed for applications where oils and fats can compromise label performance.
9. SP Group
Spain-based SP Group develops flexible food packaging. In September 2026, it highlighted mono-material structures as a route to better recyclability under PPWR.
The company’s food focus makes it relevant to processors looking for European converting support, not only global scale.
Its inclusion also reflects an important market point. The European mono-material sector is not limited to the largest multinational converters. Regional specialists can be highly competitive where technical support, shorter supply chains and category experience matter.
10. Gruppo Happy
Italy’s Gruppo Happy adds a rigid-packaging dimension to the ranking. Its APS system is positioned as recyclable mono-material food packaging. The wider portfolio includes MAP and fresh-food tray technologies.
That matters because mono-material is not only a pouch or flow-wrap discussion. Supermarkets also need recyclable solutions for trays, meat and fish packs, fresh food and modified-atmosphere applications.
What is mono-material food packaging?
Mono-material food packaging is designed mainly around one material family, such as polyethylene, polypropylene or PET. This makes the pack easier to sort and recycle than a structure combining incompatible materials.
It may still contain very small functional layers, inks, adhesives or coatings where recycling-design rules permit them.
That last point is important. “Mono-material” does not always mean literally 100% one polymer.
High-barrier food packs may use a very thin EVOH layer while still being designed for a PE or PP recycling stream. Kuraray, for example, is promoting thin EVOH barrier layers for mono-PE and mono-PP structures as PPWR changes packaging design.
Why PPWR is accelerating mono-material packaging
The EU Packaging and Packaging Waste Regulation changes the economics of packaging design.
Recyclability, material minimisation and future performance grades will increasingly affect two things. They will shape what FMCG manufacturers and retailers can place on the market. They will also shape what they pay through producer-responsibility systems.
This does not mean every multi-material pack should be replaced straight away. The transition has to protect food.
A 2026 life-cycle study of cured-meat packaging found that a mono-material alternative could produce a worse environmental result. This happened when shorter shelf life increased food waste.
For grocery procurement, that is a critical warning: food waste can outweigh the packaging saving.
PE vs PP vs PET: which mono-material route is best?
| Material | Typical strengths | Typical applications | Main buyer question |
|---|---|---|---|
| PE | Sealability, toughness, flexible-film recycling route | Pouches, bags, frozen and dry food | Can barrier and stiffness meet the current specification? |
| PP | Heat resistance, stiffness, clarity | Flow-wrap, snacks, some retort and lidding uses | Will it run at the required speed and temperature? |
| PET | Rigidity, clarity, established tray applications | Ready-meal and fresh-food trays | Is the complete tray/lid system compatible with recycling? |
What supermarket buyers should ask before approving a supplier
- What exactly is the structure? Ask for the full layer composition, not the marketing name.
- Which recycling guideline has assessed it? A generic “recyclable” statement is not enough.
- What shelf-life work has been completed? Test on the real food and distribution chain.
- What happens to line speed? Record sealing temperature, rejects, downtime and scrap.
- Does the supplier have backup production? A new material with only one approved converting site can increase supply risk.
- What happens to EPR cost? Model the future fee as well as the current film price.
- Can it survive ecommerce? Leakage and compression requirements may differ from store distribution.
Which food categories are easiest to convert?
Dry foods, snacks, pet food and some frozen products can be easier. Their moisture and oxygen needs may be less demanding than chilled protein, cheese or retort products. But there is no universal order.
Coffee, for example, needs strong aroma and oxygen protection. Frozen packs need toughness at low temperatures.
High-barrier meat, cheese and ready meals are more technically demanding, but suppliers are making rapid progress. The decision should be made by product and packing line, not by category headline.
Does mono-material packaging cost more?
The film price can be higher or lower depending on structure and volume. Buyers should calculate total packed cost rather than price per kilogram.
A cheaper film that reduces packing speed or increases rejects can cost more overall.
Equally, a higher material price may be offset by lower EPR fees, lower pack weight or better logistics.
Can mono-material packaging run on existing equipment?
Often yes, but not automatically. Different films have different stiffness, heat resistance, coefficient of friction and sealing windows.
The supplier should run line trials at commercial speed. It should document any changes to jaws, temperature, dwell time, tension or machine settings.
What evidence should buyers request for recyclability?
Buyers should request:
- the exact design-for-recycling assessment used
- the country or recycling stream to which it applies
- material composition, inks and adhesives
- any conditions attached to the claim
Recycling infrastructure is not identical across Europe. A pack designed for recycling does not guarantee that every household can recycle it today.
What happens next?
Mono-material food packaging will move from innovation projects into routine tendering as PPWR implementation advances.
The suppliers most likely to win large grocery programmes will not necessarily have the most novel film. They will be those that can prove food protection, line performance, regulatory readiness, production continuity and end-of-life compatibility at the same time.
For supermarket buyers, that changes the tender. Packaging price remains important. But the winning specification increasingly sits where food waste, manufacturing efficiency and recycling economics meet.
Those same issues are now being discussed directly in supplier-led technical forums. These include the October 2026 programme covered in GTN’s MULTIVAC Meat & Minds Summit report.
Editor’s Note: Grocery Trade News reviewed current supplier product information and European packaging guidance in September 2026. Company scale is stated only where publicly disclosed. Technical claims should be validated against the exact packaging structure, food application, packing equipment and destination-market recycling system before procurement approval.