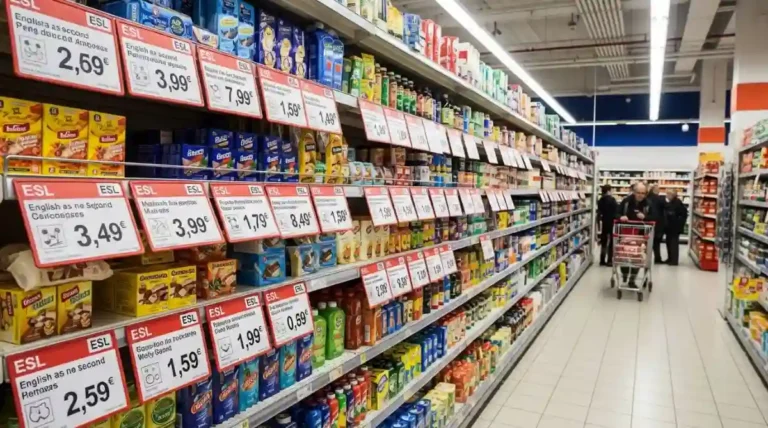

Electronic shelf labels have moved from a store technology pilot into supermarket infrastructure. In 2026, some of Europe’s largest grocery groups are rolling out millions of digital labels across hundreds of stores. These labels link shelf-edge pricing directly with central product, promotion and inventory systems.
Scale matters. A supermarket does not buy an electronic shelf label in isolation. It buys:
- a wireless network
- a management platform
- a mounting system
- an integration layer
- an installation programme
- a multi-year support model
Together, these may eventually control tens of millions of price points.
This ranking identifies eight electronic shelf label companies with clear relevance to supermarket operators.
Grocery Trade News ranked them using:
- documented retail deployment scale
- current company size where publicly disclosed
- proven supermarket projects
- platform depth
- the ability to support multi-store rollouts
Revenue is included where the vendor publishes it. Private companies are not assigned estimated turnover.
Top electronic shelf label companies for supermarkets
| Rank | Company | Latest disclosed scale | Supermarket evidence | Core strength |
|---|---|---|---|---|
| 1 | Vusion | €1.527bn adjusted 2025 revenue. 1,200 employees. 650m ESLs | Morrisons 497-supermarket programme. 75,000 stores globally | Enterprise ESL and connected-store platform |
| 2 | Pricer | SEK 2.148bn 2025 sales. 210 employees year-end. 380m+ ESLs delivered | 28,000+ stores in 80+ countries | High-reliability shelf communication and store digitalisation |
| 3 | Hanshow | Private. solutions in 55,000+ stores across 70+ countries | 560,000+ ESLs planned across 84 Alcampo supermarkets in 2026 | Large global ESL portfolio and digital-store infrastructure |
| 4 | SOLUM | Private ESL segment. Samsung technology roots | 200+ Waitrose stores by July 2026 | Newton ESL platform and enterprise deployments |
| 5 | Displaydata | Private | Kaufland rollout across 1,545 stores in 7 countries | Fully graphic shelf-edge displays and rapid markdowns |
| 6 | ZKONG | Private. 100,000+ shops equipped by 2023 | Global cloud-ESL deployments | SaaS and cloud-managed ESL infrastructure |
| 7 | Delfi Technologies | Private. 4,600+ active Breece installations | Strong Nordic and European grocery footprint | ESL implementation, integration and regional support |
| 8 | Minew | Private. customers in 100+ countries and regions | ESL solutions across retail and supermarket applications | IoT hardware, tags and flexible ESL systems |
How Grocery Trade News ranked the ESL companies
This is not a ranking of the cheapest labels. Hardware price is only one part of an electronic shelf label project.
The ranking gives more weight to actual retail deployment, supermarket references, network reliability, integration and support.
A supplier with a slightly cheaper tag can become more expensive if:
- installation takes longer
- battery replacement is frequent
- wireless coverage is weak
- the retailer has to build custom interfaces around the platform
Public financial data also needs context. Vusion and Pricer publish audited group results. Hanshow, Displaydata, Delfi, ZKONG and Minew are privately held or do not disclose comparable ESL revenue publicly.
SOLUM operates ESL alongside other electronics activities. Those differences make revenue an indicator of scale, not a standalone ranking method.
1. Vusion
- Founded: 1992 roots
- 2025 adjusted revenue: €1.527 billion
- Employees: Around 1,200
- Installed base: 650 million electronic shelf labels across 75,000 stores
Vusion was previously known as VusionGroup and SES-imagotag. It is currently the largest publicly disclosed ESL and connected-store specialist in this ranking by revenue and installed base.
The company has moved far beyond electronic price tags. Its platform combines ESLs with shelf monitoring, computer vision, retail media and cloud services. That wider architecture is one reason large retailers increasingly treat the supplier as store infrastructure rather than a label vendor.
Key facts
In 2025, Vusion reported adjusted revenue of €1.527 billion and adjusted EBITDA of €277 million. The group says its technology is deployed in around 75,000 stores, representing 650 million electronic shelf labels.
The grocery evidence is substantial. Morrisons selected Vusion for a programme covering 497 supermarkets and around 10.8 million electronic shelf labels.
At that scale, the business case is not just replacing paper. Central pricing, promotion execution, labour deployment and future shelf-level applications all become part of the same infrastructure decision.
What buyers should check
GTN has previously covered Vusion’s growing position in global retail technology. For supermarket procurement teams, the key advantage is enterprise scale.
The matching risk is platform complexity. That makes contract scope, licences and long-term integration costs important.
2. Pricer
- Founded: 1991, Sweden
- 2025 net sales: SEK 2.1479 billion
- Employees: 210 at year-end 2025
- Installed base: 380 million+ labels in 28,000+ stores across 80+ countries
Pricer is one of the longest-established companies in electronic shelf labelling. The Swedish listed group has spent more than three decades building digital shelf-edge systems. Grocery retail remains a central part of its customer base.
Its 2025 annual report shows SEK 2.1479 billion in net sales. The company had 210 employees at year end. It says it has delivered more than 380 million labels into more than 28,000 stores.
Why it matters to supermarket buyers
Pricer’s strength is operational reliability. In supermarkets, price changes cannot simply be sent from head office. The retailer needs confidence that the shelf actually received and displayed the update.
That acknowledgement process becomes critical when thousands of changes are pushed during promotions or inflation-driven repricing.
The group also has established relationships with large international retailers including Carrefour. Its Pricer Plaza platform adds cloud-based store services on top of the label infrastructure.
For grocery operators, Pricer is particularly relevant where pricing accuracy and shelf communication are treated as business-critical systems rather than visual merchandising.
New supermarket trial evidence also points to a wider commercial role. Pricer Avenue increased sales by up to 4.8% in an East of England Co-op trial. This highlights potential applications in promotions, shopper engagement and in-store retail media.
3. Hanshow
- Founded: 2012
- Revenue: Not publicly disclosed
- Global footprint: 55,000+ stores in 70+ countries
- Customer reach: Works with more than half of the world’s top 100 retail companies
Hanshow has become one of the largest global ESL providers in little more than a decade.
The company combines electronic labels with shelf monitoring, digital displays and other connected-store systems.
Key facts
Its current grocery deployments show why it ranks highly. In Spain, Alcampo is investing €3.8 million in more than 560,000 Hanshow labels across 84 supermarkets during 2026.
The project includes labels suitable for fresh and low-temperature areas. It is designed to reduce manual paper labelling while creating a real-time shelf data layer.
That project is useful for buyers because it shows the true scale of a supermarket rollout. Hundreds of thousands of labels need to be mounted, paired, mapped to product data and supported without disrupting trading.
Hanshow says its solutions are now used in more than 55,000 stores across over 70 countries.
The company has also expanded European partnerships, including a strategic relationship with Delfi Technologies.
What buyers should check
For international supermarket groups, Hanshow’s strength is global deployment capacity combined with a wide hardware range.
Procurement teams should still test local support, freezer performance, mounting and integration in the specific country where the rollout will take place.
4. SOLUM
- Established: 2015
- Origins: Spin-off from Samsung Electro-Mechanics
- Revenue: ESL segment not separately comparable in public reporting
- Core platform: Newton electronic shelf labels and AIMS management software
SOLUM combines electronics manufacturing heritage with a rapidly expanding retail technology business.
The company was created in 2015 when several businesses were spun out of Samsung Electro-Mechanics. These included power modules, tuners and electronic shelf labels.
Key facts
The strongest supermarket proof point in 2026 is Waitrose. By 24 July, SOLUM’s Newton Pro electronic shelf labels had been deployed in more than 200 Waitrose stores. The UK-wide programme is continuing.
For Waitrose, the system centralises price and product-information updates and reduces manual ticket replacement.
For SOLUM, the rollout shows it can support a large premium grocery estate while continuing deployment store by store.
SOLUM has also expanded ESL projects across cooperative grocery, electronics retail and international markets.
Its hardware manufacturing background can be valuable where retailers want a supplier with control over product engineering as well as software.
5. Displaydata
- Headquarters: United Kingdom
- Revenue: Not publicly disclosed
- Core strength: Fully graphic electronic shelf-edge displays
Displaydata has built a strong position around high-quality graphic shelf displays. It does not treat ESLs only as small digital price tickets.
Its Kaufland project is one of the largest grocery references in the market.
Displaydata says its enterprise ESL solution is being rolled out across Kaufland’s 1,545 stores in:
- Germany
- Poland
- Slovakia
- Croatia
- Czech Republic
- Romania
- Bulgaria
Why it matters to supermarket buyers
Kaufland’s use case shows an important side of ESL economics: markdown speed.
In fresh produce and other short-life categories, stores can change prices centrally within seconds. That gives them more options to protect margin while reducing waste.
Displaydata’s larger graphic labels can also carry promotional messaging and extra product information. That creates more shelf-edge flexibility.
But retailers should be clear about where larger displays generate enough commercial value to justify the extra hardware cost.
6. ZKONG
- Founded: 2006
- Revenue: Not publicly disclosed
- Scale reference: 100,000+ shops equipped with ESL products by 2023
ZKONG approaches the market from a cloud-first direction. The company developed wireless communications before moving into smart retail. In 2015, it launched what it describes as an early SaaS-based ESL solution with Alibaba.
Its own company material says more than 100,000 shops had been equipped with ZKONG ESL products by 2023. The company has also expanded localisation across Europe, North America and Asia.
For supermarket groups, the attraction is central cloud management and a broad hardware portfolio.
That can simplify multi-store administration, particularly for retailers operating different store formats.
What buyers should check
The procurement question is support depth. Large supermarkets should test regional engineering coverage, security, data hosting and escalation processes. They should not judge the platform only on device specification.
7. Delfi Technologies
- Base: Denmark
- Experience: More than 30 years in digital retail systems
- Active Breece installations: 4,600+
Delfi Technologies is smaller than the global ESL manufacturers above. But its role shows why implementation partners matter. Its Breece platform is designed around digital price management, integration and day-to-day retailer support.
The company says it has more than 4,600 active Breece installations across Europe. Its customer base includes supermarkets, convenience stores and other retail formats.
Delfi has also widened the hardware available through Breece. Its strategic partnership with Hanshow adds Hanshow labels to a platform that already supports Displaydata systems. This gives customers more choice without replacing the underlying Breece architecture.
This model can suit regional supermarket groups that want one partner responsible for integration and deployment, rather than dealing directly with a global hardware producer. Similar integration dynamics are already visible across the Baltic supermarket technology market.
8. Minew
- Founded: 2007
- Revenue: Not publicly disclosed
- Geographic reach: Customers in more than 100 countries and regions
- Core background: IoT hardware, Bluetooth, RFID and electronic shelf labels
Minew is the smallest grocery-specific player in this ranking by disclosed supermarket evidence. But it has a long IoT manufacturing background and a broad international customer base.
The company has developed electronic shelf labels alongside Bluetooth and RFID devices. It now runs a dedicated ESL product offer. Its technology has been positioned for supermarkets, warehouses, beauty stores and other retail environments.
What buyers should check
For a large supermarket group, Minew would require more detailed reference checking than the established grocery leaders above.
For smaller chains, distributors and technology integrators, however, its broader IoT portfolio and flexible hardware approach can be relevant.
That difference is why Minew ranks eighth rather than being excluded. Not every ESL procurement exercise is a 10-million-label national rollout.
Major supermarket ESL rollouts in 2026
| Retailer | ESL supplier | 2026 deployment reference | Why it matters |
|---|---|---|---|
| Morrisons | Vusion | 497 supermarkets. around 10.8m ESLs | One of Europe’s largest grocery-wide shelf digitisation programmes |
| Alcampo | Hanshow | 560,000+ ESLs across 84 supermarkets. €3.8m investment | Shows capex and installation scale in a national grocery network |
| Waitrose | SOLUM | 200+ stores live by July 2026 | Large premium-grocery rollout with central price management |
| Kaufland | Displaydata | Rollout across 1,545 stores in seven European countries | Links ESLs directly with markdown speed, margins and waste reduction |
What electronic shelf labels actually change inside a supermarket
The most visible change is obvious: paper tickets disappear. The bigger operational change happens behind the shelf.
The main changes are:
- Central pricing: pricing teams can push updates centrally rather than asking each store to print, sort and replace tickets.
- Less store labour: staff spend less time on repetitive price changes.
- Consistent promotions: promotions can start and finish more consistently.
- Better audit trails: systems can confirm whether an update reached the label.
ESLs can also support picking and replenishment. Flashing LEDs, location data and product information can help staff find items faster. Larger displays create new options for promotions and retail media.
Fresh categories add another use case. Faster markdowns can help supermarkets reduce waste and manage short shelf life. Staff no longer need to walk the store with bundles of replacement labels.
The lowest label price can create the highest project cost
A supermarket tender should therefore compare total cost of ownership, not price per tag.
| Procurement area | What buyers should test | Commercial risk |
|---|---|---|
| Wireless reliability | Update speed, acknowledgement and coverage in a live supermarket | Incorrect or delayed shelf prices |
| Battery life | Real update frequency, temperature and display behaviour | Large future replacement labour bill |
| Freezer and chiller use | Low-temperature models and battery performance | Failure in high-value chilled/frozen areas |
| Mounting | Existing shelving, rails, hooks and fresh fixtures | Hidden installation capex |
| Integration | POS, ERP, promotion, product and inventory APIs | Custom development and rollout delays |
| Cybersecurity | Device authentication, gateways, cloud access and patching | Price infrastructure becomes an attack surface |
| Support | Local engineers, spares, escalation and service levels | Slow recovery when stores fail |
| Lifecycle | Five-to-seven-year device, licence and replacement model | Low initial capex but high operating cost |
Are ESLs the same as dynamic pricing?
No. Electronic shelf labels are the infrastructure used to display centrally managed prices. A retailer can change prices more quickly with ESLs, but the pricing policy still sits with the retailer and its systems.
For supermarkets, the immediate business case is usually operational:
- price accuracy
- labour reduction
- promotion execution
- faster markdowns
Dynamic or algorithmic pricing may be added later, but it is not a requirement for an ESL rollout.
That distinction matters. Procurement teams need to separate the value of digital shelf infrastructure from the pricing strategy that may eventually run through it.
Frequently Asked Questions
Which is the largest electronic shelf label company?
Vusion is the largest publicly disclosed ESL specialist in this ranking. It reported €1.527 billion in adjusted 2025 revenue, with 650 million labels across around 75,000 stores.
Which supermarkets are rolling out electronic shelf labels in 2026?
Major programmes include Morrisons with Vusion, Alcampo with Hanshow, Waitrose with SOLUM and Kaufland with Displaydata. Morrisons’ programme covers 497 supermarkets and around 10.8 million labels.
What should supermarkets compare when buying ESLs?
Buyers should compare total cost of ownership, not price per tag. Key areas include wireless reliability, battery life, freezer use, mounting, integration, cybersecurity, support and lifecycle costs.
What happens next?
Supermarket ESL investment is moving towards connected shelf infrastructure rather than standalone digital labels.
The strongest vendors are adding these around the same shelf edge:
- computer vision
- retail media
- inventory signals
- picking support
- cloud analytics
That will make vendor selection more strategic.
A retailer choosing an ESL platform in 2026 may still be using the same network several years later. By then it may be introducing automated markdowns, shelf cameras, store media or AI-assisted replenishment.
Vusion, Pricer, Hanshow and SOLUM currently have the clearest combination of scale and major grocery references.
Displaydata remains important through large European supermarket deployments. ZKONG, Delfi and Minew widen the market for retailers with different integration, service and cost requirements.
The winning technology will not simply be the label with the best specification. It will be the system that can:
- operate reliably across thousands of fixtures
- integrate with supermarket data
- reduce work at store level without creating a new layer of complexity
Editor’s Note: Grocery Trade News reviewed FY2025 annual reports, current company disclosures and supermarket deployment announcements available up to 8 September 2026. Public revenue is shown only for companies that disclose comparable figures. Private-company turnover has not been estimated.
Retail rollout figures include current programmes announced by Vusion, Hanshow, SOLUM, Displaydata and their supermarket customers. Rankings reflect grocery deployment scale, technology footprint, integration capability and supermarket operating relevance rather than revenue alone.